The 2s10s Spread Turned Positive — Why the Slope Matters More
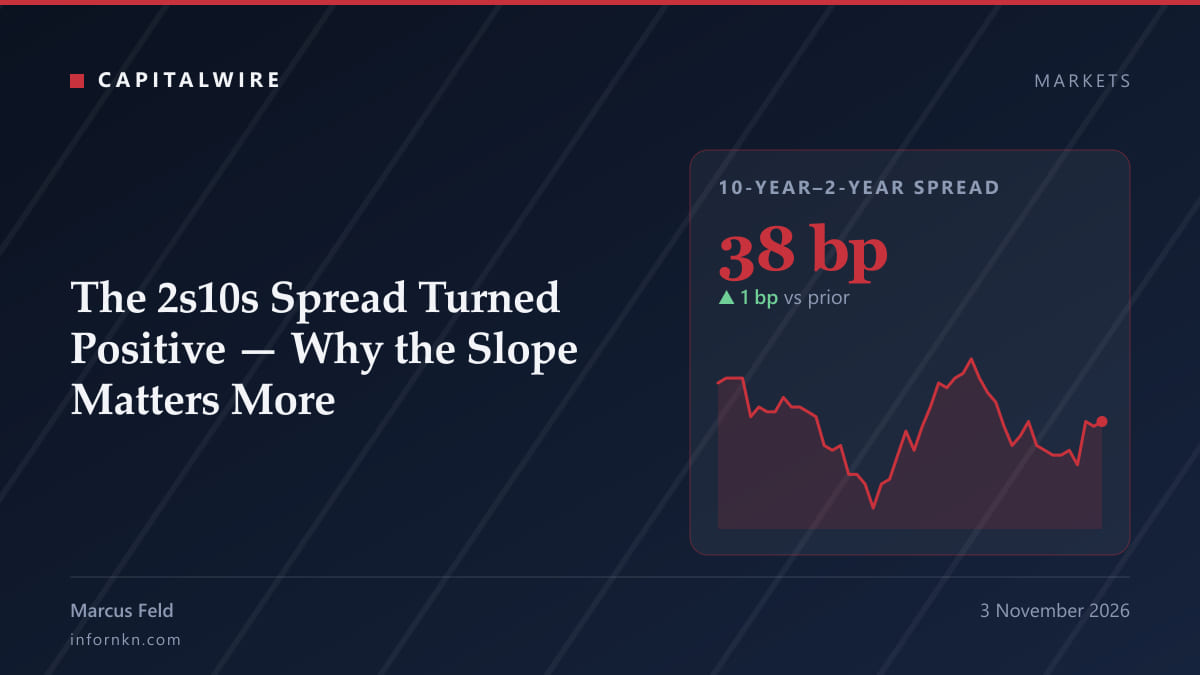
The two-year ten-year spread is now 38 basis points, down from 72 at the start of the year. The curve is still positively sloped, but the long end is flattening.
A positively sloped Treasury curve is usually read as a vote of confidence: the market expects growth and wants more yield to lend long. The two-year ten-year spread is now 38 basis points, which is positive, but the more useful question is what the slope has been doing. A year ago the same spread was 53 basis points, and it peaked at 72 in early January before compressing to 41 at the end of the third quarter.
The compression is a bull flattener. The ten-year is 4.94% and the two-year is 4.56%, so the front of the curve is doing the work. When the short end lags the long end, it usually reflects a market that has moved its rate-cut expectations forward, not one that fears recession. An inverted curve signals the latter, and this one is not inverted.
The sign matters less than the slope. A positive spread that is shrinking says the curve is normalising by flattening at the long end, which is what happens when the Fed is done hiking but the economy has not rolled over. The recession warning an inverted curve carries is absent, but so is the steepening that would signal a recovery trade. With the spread at 38 basis points, it sits in the lower part of its one-year range.
What would change the reading. A move back above 72 basis points would mark a genuine steepener and a growth bet. A break back below zero, with the two-year again above the ten-year, would be the inversion signal markets watched from 2022 to 2024, and that is not what the current 38 basis points is showing. Until then, the curve is best read as neutral: normal, but narrowing.
Elsewhere
- 10-Year Treasury Constant MaturityFRED
The long leg of the spread this page's figures are computed from.
- 2-Year Treasury Constant MaturityFRED
The short leg of the spread.
- 10-Year minus 2-Year Treasury YieldFRED
FRED's own measure of the same spread, used here for the historical comparisons.
Sources
- FRED series DGS10, 10-Year Treasury Constant Maturity, observed 2026-10-30
- FRED series DGS2, 2-Year Treasury Constant Maturity, observed 2026-10-30
- FRED series T10Y2Y, 10-Year minus 2-Year Treasury Yield, observed 2026-11-02
More from CapitalWire

The 10-Year's 2026 Rise Is a Real-Rate Story
Nominal yields are up 79 basis points this year. Real yields account for 69 basis points of that, inflation expectations for 9.

Treasury Curve Flattens as Jobs Data Pulls December Hike Odds to 68%
Two-year Treasury yields fell six basis points to 4.61% and ten-year yields slipped seven to 4.98% after October payrolls undershot, leaving the 2s10s spread near 37 basis points as December Fed hike odds eased from 78% to roughly 68%.

Treasury Market Reprices as Inflation Expectations Slip Below 2.3%
Long-dated U.S. government bonds have rallied sharply, pulling ten-year yields below 3.6% and breakeven inflation to a two-year low.
Reader discussion